Published on
December 24, 2024

You've seen the term on a broker's listing or in a valuation report and you're not sure if it's the same as profit, the same as EBITDA, or something else entirely. Short answer: SDE stands for Seller's Discretionary Earnings, and it's the cash flow measure buyers use to price small and mid-sized businesses [2]. It's not the same as net income, and it's not quite the same as EBITDA either, though people use them interchangeably all the time. Getting this wrong costs sellers real money at the negotiating table.
SDE stands for Seller's Discretionary Earnings: the total financial benefit a full-time owner-operator gets from the business in a year, before tax [3]. It starts with pre-tax net income and adds back owner compensation, interest, depreciation and amortization, and discretionary or one-time expenses. Think of it as an answer to the question a buyer actually cares about: what would I, as the new owner, actually take home?
The formula, in plain terms: SDE = Pre-Tax Net Income + Owner's Compensation + Interest + Depreciation & Amortization + Discretionary/One-Time Add-Backs [2] [4]. That last bucket includes things like the owner's car lease, a family member's inflated salary, one-off legal fees, or a flood claim that won't repeat [2]. The IBBA's own glossary defines it the same way: earnings before taxes, non-operating and non-recurring items, D&A, interest, and the owner's full compensation package [5].
Two quick notes on things people search but that aren't really finance questions. If you've seen SDE used as slang, it usually stands for something unrelated and mildly insulting on forums [6] - not what we're talking about here. And if you've seen SDE attached to a music group's "debut," that's a different acronym entirely, unrelated to business valuation. In a finance or M&A context, SDE always means Seller's Discretionary Earnings.
You calculate SDE by starting with pre-tax net income from the P&L, then adding back non-cash and owner-specific items that a buyer wouldn't inherit the same way. For a business under about $5M in revenue, this is usually a clean process. For a growth-stage company, it takes more judgment, because some of what looks discretionary is actually replacement management cost.
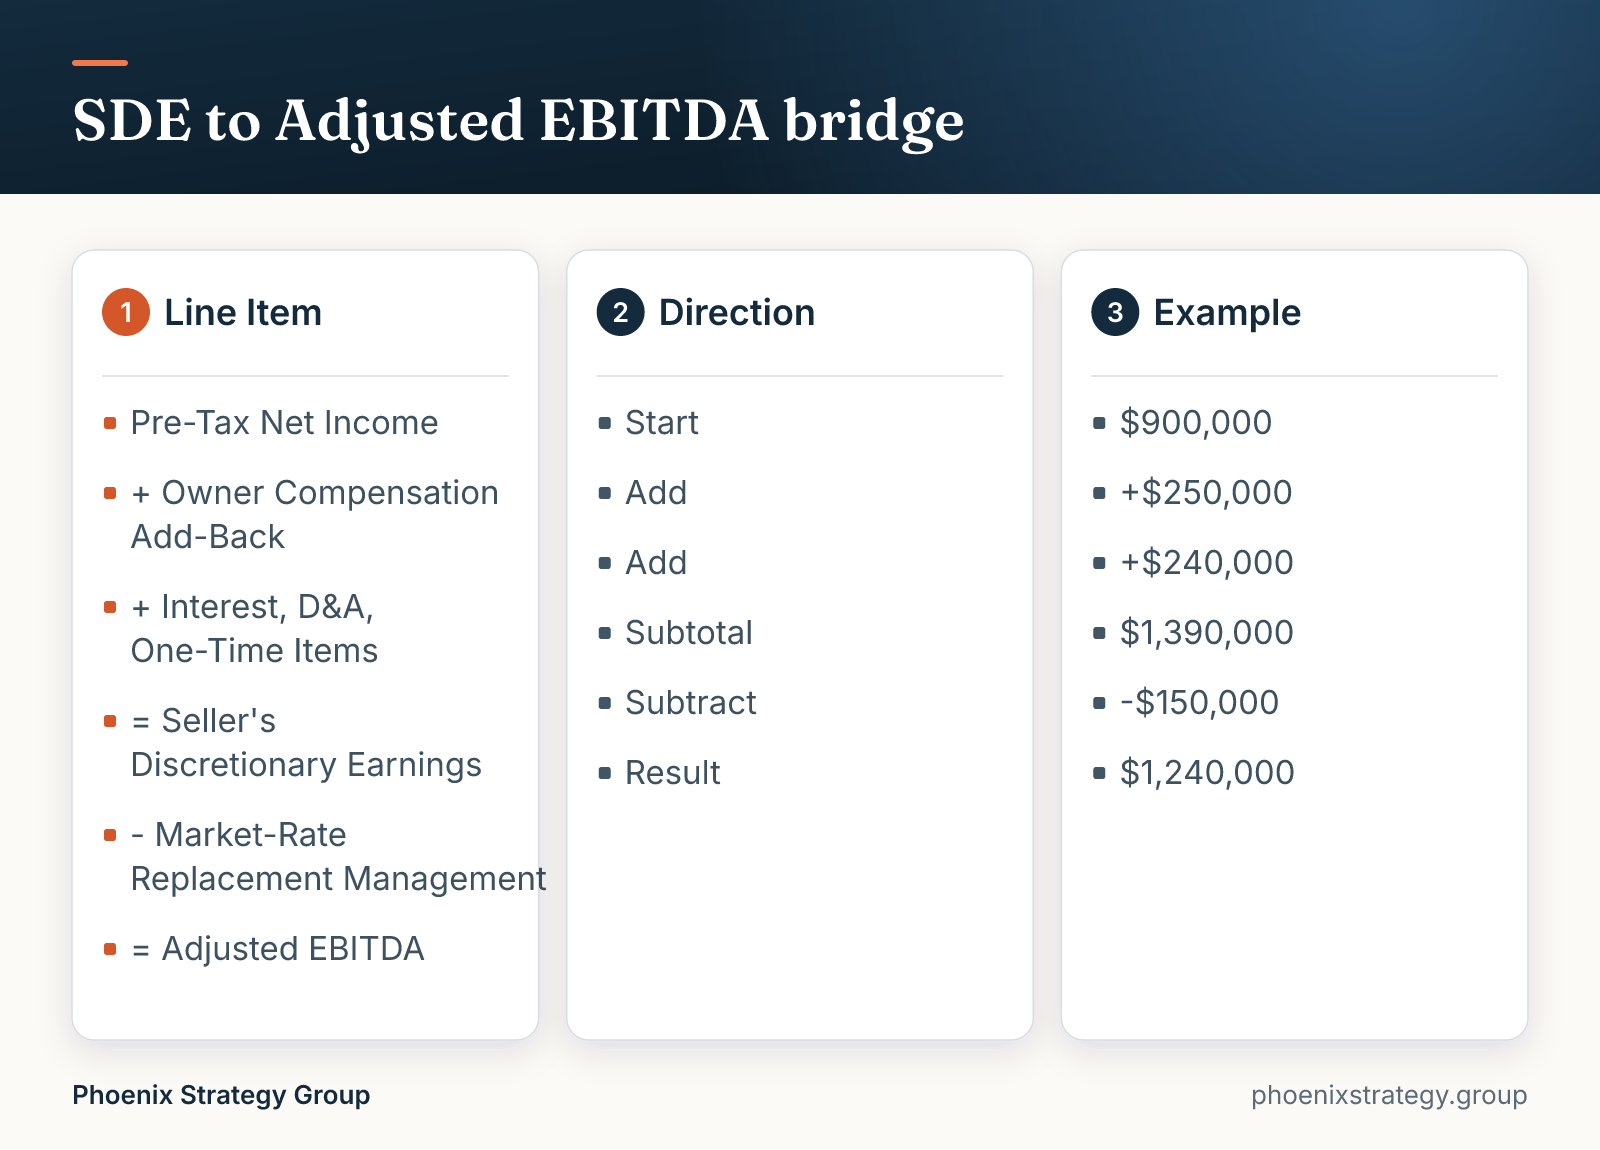
Picture an $8M-revenue services company. Pre-tax net income is $900,000. The owner draws $250,000 in salary, well above the $150,000 a market-rate general manager would cost to do the same job. Add back $80,000 in interest expense and $120,000 in D&A. There's also a one-time $40,000 legal settlement that won't recur. Add it all up: $900,000 + $250,000 + $80,000 + $120,000 + $40,000 = $1,390,000 in SDE.
That's the textbook calculation. But notice the owner comp add-back assumed the owner does nothing that needs replacing. If a GM has to be hired to run daily operations after the sale, a buyer will subtract that $150,000 replacement cost right back out. That's the step most self-calculated SDE numbers miss, and it's exactly why growth-stage companies need a second metric once they get big enough.
SDE, Adjusted EBITDA, and net income all measure profitability, but they answer different questions for different buyers. Net income is what your tax return says. SDE assumes one owner runs everything and gets full credit for it. Adjusted EBITDA assumes a management team is in place and only counts what the business earns independent of any one person.
| Metric | Definition | Typical Buyer | Typical Multiple Range | When It's Used |
|---|---|---|---|---|
| Net Income | Bottom-line profit after all expenses and taxes | Individual buyers, lenders doing basic checks | Rarely multiple-based directly | Tax filings, basic profitability check |
| SDE | Net income plus owner comp, interest, D&A, and discretionary add-backs [2] | Owner-operator buyers, SBA-financed buyers | 2-3x for small service businesses, 3-4x with some management depth [7]; average closed-deal multiple around 2.7x [8] | Businesses under roughly $5M revenue where one owner runs the show |
| Adjusted EBITDA | EBITDA further refined by a Quality of Earnings review [9] | Private equity, strategic acquirers, growth investors | 4-6x for $1M-$5M EBITDA, 6-9x for $5M-$25M, 8-12x above that [7] | Businesses with a management layer, recurring revenue, and institutional buyers in the mix |
You should move from SDE to Adjusted EBITDA once revenue crosses roughly $5M or once you have a manager running day-to-day operations without you [9]. The real test isn't revenue size on its own, it's whether the business still depends on one owner's labor. The IBBA calls this the operational dependence test, and most brokers apply it whether or not the company hits a specific number [9].
Most companies between $3M and $7M in revenue sit in a gray zone [9]. This is exactly the stage where founders get burned. They present a broker's SDE number to a private equity buyer, and the buyer's diligence team backs out a replacement GM salary of $200,000 to $400,000, which compresses the multiple hard [10]. The founder feels blindsided, but the buyer was just doing standard Adjusted EBITDA math.
If you're planning to sell or raise capital in the next 12 to 24 months and you're anywhere near that $3M-$7M band, don't wait for a buyer to make this adjustment for you. Have your CFO or advisor build the Adjusted EBITDA bridge now: subtract a market-rate replacement salary, document which add-backs are truly one-time, and get comfortable with the lower, more defensible number before it shows up in a Letter of Intent. This is the same discipline behind good unit economics work: buyers pay for numbers they can trust, not numbers that look best on day one.
Defensible add-backs are ones tied to a real, provable, non-repeating cost; risky add-backs are anything a buyer's diligence team can poke a hole in with one follow-up question. Lenders and Quality of Earnings reviewers reject 10 to 30 percent of a typical seller's add-back list [1], so the goal isn't to list everything, it's to list what survives.
SDE and Adjusted EBITDA don't just set your multiple, they shape how a buyer wants to pay you. A shaky, add-back-heavy earnings number pushes buyers toward earnouts and seller notes instead of cash at close, because they want you to prove the number is real before they pay for it in full.
If your customer base is concentrated in a few accounts, expect a buyer to lean on an earnout or a retention condition rather than handing over full value up front [12]. Working capital is its own fight: buyers and sellers agree on a target level of current assets minus current liabilities that has to be delivered at closing, and disputes here can eat into your proceeds after the headline price is already agreed [13]. A defensible SDE or Adjusted EBITDA bridge, built ahead of time, gives you leverage in all three of these conversations, not just the multiple.
This is also where cash flow and SDE intersect directly. SDE is meant to approximate free cash flow available to an owner [4], and buyers structuring an earnout are betting on that cash flow continuing after you leave. If your SDE relied heavily on your personal relationships or your daily hands-on labor, expect the buyer to price that risk into the earnout terms, not just the multiple.
SDE meaning boils down to this: pre-tax net income plus owner comp, interest, D&A, and honest one-time add-backs, used mainly for owner-operated businesses under roughly $5M in revenue. Past that size, or once a management layer exists, buyers want Adjusted EBITDA with a Quality of Earnings review standing behind it, and SDE stops being the number that matters. Get the bridge between the two built early, with defensible add-backs and a realistic replacement management cost, and you protect both your multiple and your buyer pool. If you'd rather not build this by hand, Dear CFO builds it from your QuickBooks, alongside the ltv/cac and gmv metrics that round out how buyers actually judge a growth-stage company.
Not exactly. SDE starts from bottom-line profit but adds back owner-specific and non-cash items, so it's closer to the total cash benefit an owner-operator gets than a strict accounting profit figure [14].
EBITDA adds back interest, taxes, depreciation, and amortization but leaves owner compensation as an operating cost, which works for businesses with professional management already in place [15]. SDE goes further and adds back the owner's full pay too, which fits owner-operated businesses where the current owner's replacement isn't factored in yet.
A business generating $300,000 in SDE typically sells somewhere between $600,000 and $1,200,000, depending on industry and risk profile [16].
Outside of business valuation, SDE is used as unrelated slang online [6], and it also shows up as a different acronym in fan and pop-culture contexts referring to a group's debut. Neither use has anything to do with the financial meaning of SDE covered in this article.

About the author
Partner, Phoenix Strategy Group
Ethan Lu is a Partner at Phoenix Strategy Group, where he works as a fractional CFO helping founder-led companies maximize their exit value. He currently oversees more than $200M in client enterprise value and has been part of multiple eight-figure exits. Before PSG he was an asset manager and investor for a San Diego family office, where he sat on the investment committee for more than $1B in assets. A data scientist by training, he holds a B.S. in Mathematics with a minor in Accounting from UC San Diego.
Talk to a PSG CFO about your numbers
Phoenix Strategy Group does CFO work for growth-stage companies.
Schedule a call