Published on
May 28, 2025

A dynamic discounting solution is software that lets you pay a supplier's invoice early in exchange for a discount that slides with how many days early you pay, funded directly out of your own cash rather than a bank or third-party financier [4]. The earlier you pay, the bigger the discount, calculated automatically instead of locked to one fixed rate.
That self-funded structure is the whole point. You're not borrowing to pay suppliers early and you're not asking a bank to front the money. You're using cash that would otherwise sit in an operating account earning almost nothing, and converting it into a short-term, supplier-specific return.
Here's the math that makes it interesting. Say a supplier offers a sliding-scale discount worth 10% APR and will take payment up to 60 days before the invoice is due. Pay 60 days early and the discount works out to (10%/365) x 60, or 1.64% [2]. On a $50,000 invoice that's an $820 discount for moving payment up two months - which sounds small until you annualize it and see you just earned a 10% risk-adjusted return on cash that was otherwise parked.
In supply chain finance, dynamic discounting works by connecting your accounts payable system to a shared platform where approved invoices show suppliers a menu of early-payment dates and discount rates; the supplier picks the option that fits their cash needs and gets paid automatically [9][10]. The Global Supply Chain Finance Forum recognizes it as one of the core techniques for accelerating payment across a chain, alongside reverse factoring [9].
The workflow in practice: the supplier delivers and invoices as usual, you approve the invoice in your AP system, the platform shows the supplier a sliding scale of discount-versus-payment-date options, and once the supplier picks one, the payment and discount post automatically. No manual negotiation on every invoice.
Notice the spread. A standard 2/10 net 30 term is already paying you better than 37% annualized if you take it [1]. A true sliding-scale dynamic discounting platform just lets that rate flex with the calendar instead of forcing an all-or-nothing choice on day 10.
The difference comes down to who funds the early payment and who holds the risk. Dynamic discounting is fully buyer-funded with your own cash; supply chain finance (reverse factoring) brings in a bank priced on your credit; invoice discounting or factoring funds the supplier's receivable through a third party, with the supplier bearing the cost [4].
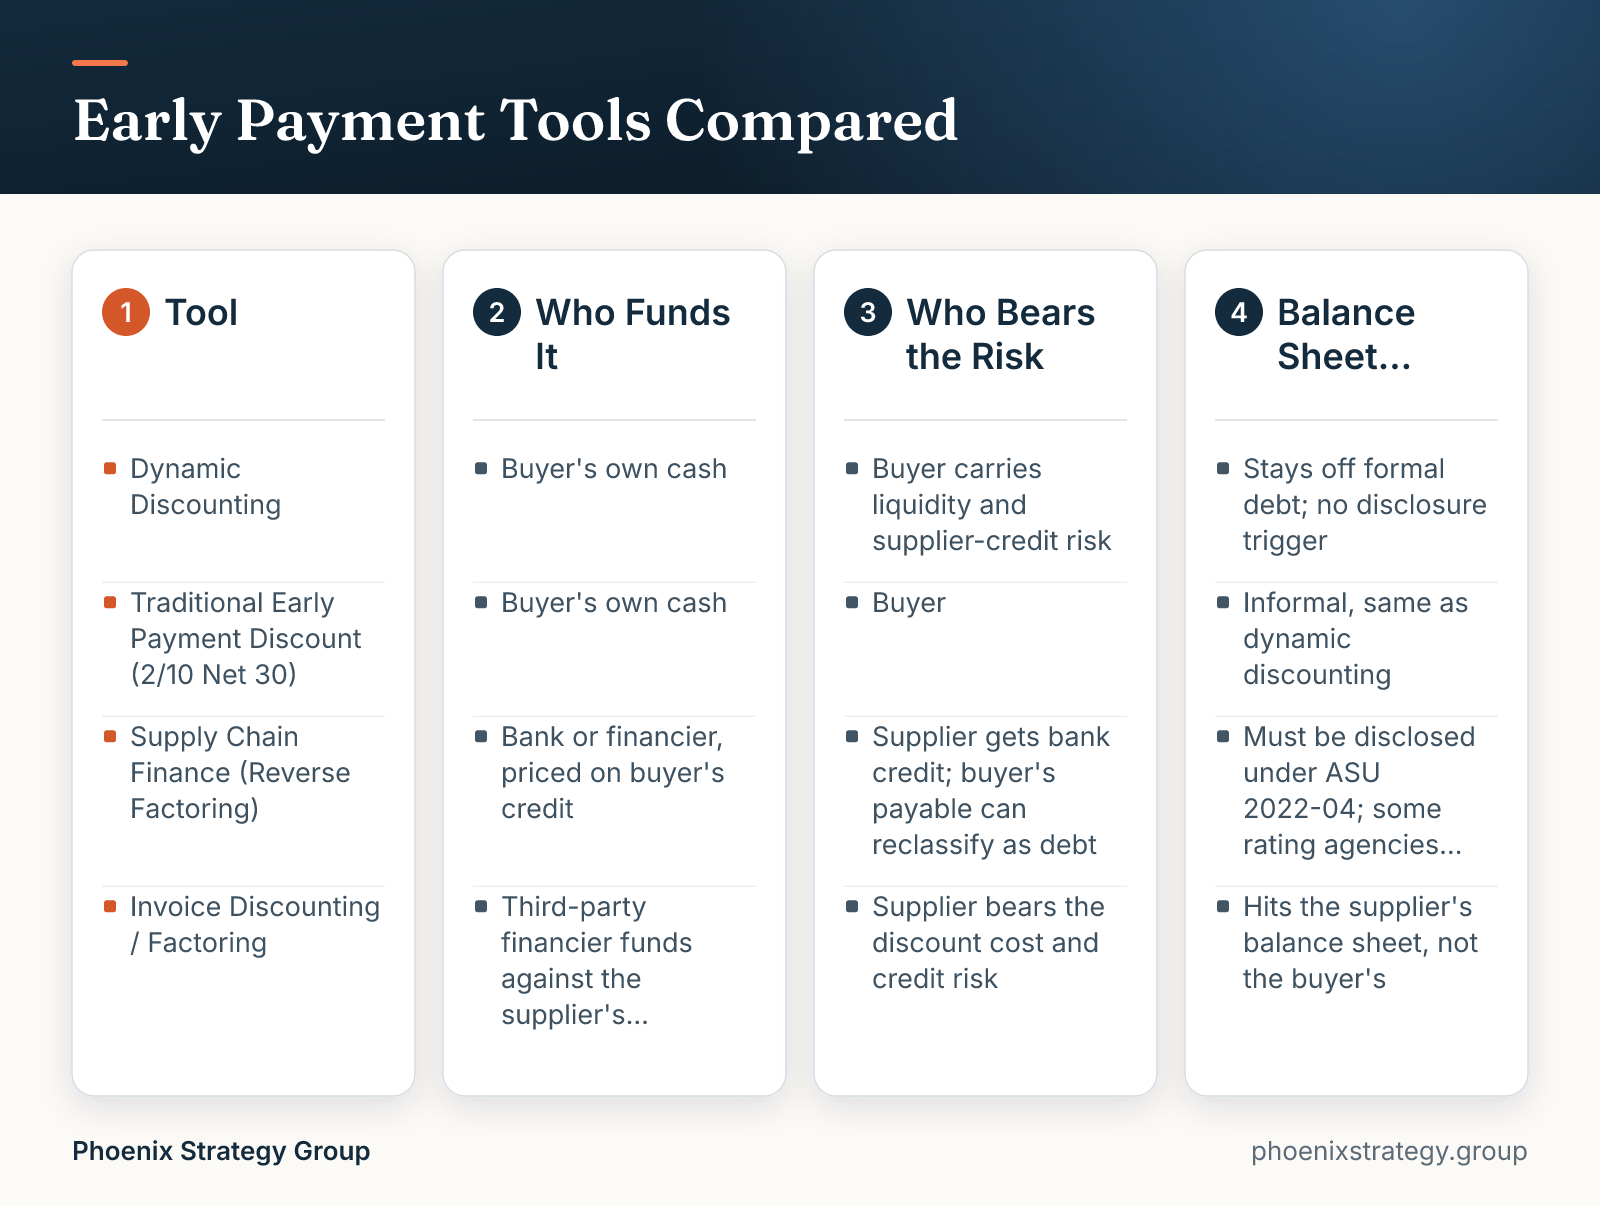
Because reverse factoring runs on the buyer's credit rating, it often gets suppliers a lower cost of funding than they could get on their own [11]. Dynamic discounting skips that entirely - no bank, no disclosure question, just your cash and the supplier's invoice.
Dynamic discounting is lower-risk than factoring because you control the cash and the counterparty is your own approved invoice, but it isn't risk-free: you're exposed to counterparty risk on the supplier, concentration risk if too much of your program runs through one vendor, and liquidity risk if you need that cash back sooner than expected.
In any early payment arrangement, credit risk is about whether the party owing the money can pay, while counterparty risk is about the platform or intermediary managing the transaction [6]. With dynamic discounting there's no intermediary financing the deal, so you've mostly traded counterparty risk for plain old operating risk: will this supplier still be around and performing in 60 days?
Concentration is the risk founders miss. Factoring platforms typically cap how much of a sales ledger can come from one debtor, often around 30% [7] - the same discipline applies in reverse. Don't let one supplier absorb half your discounting budget; spread it so no single relationship can strand your cash.
The real risk most founders underweight is liquidity risk: cash you've committed to early-pay invoices isn't sitting in your operating account anymore. If a slow sales month hits and you need that cash for payroll, you can't claw it back instantly. Size the program off cash you genuinely don't need, not off whatever's in the account this week.
You need more than a comfortable bank balance - you need cash that exceeds your operating buffer and earns less sitting idle than it would deployed into discounts. A simple rule: keep enough to cover your typical cash buffer, then run the rest through the math against your cost of capital.
The median small business holds about 27 days of cash buffer and a median daily balance near $12,100 [12]. Treat that buffer as untouchable. Anything above it is a candidate for dynamic discounting, debt paydown, or growth investment - and the decision between those three comes down to yield.
Compare the discount yield to your next-best use of that cash. A business line of credit currently runs 6.99%-7.91% [8]. If your discounting program yields 12%-37% depending on terms taken (see the table above), it beats paying down that line or letting cash sit. If your discount yield drops below your line's rate, or below what a growth investment would return, the math flips and you're better off elsewhere.
Consider a $10M revenue services company sitting on $500,000 of cash beyond its working buffer. If it deploys that $500K into a sliding-scale program averaging a 2% discount captured 20 days early across its top 15 suppliers, that's roughly $10,000 in COGS savings per cycle, repeatable multiple times a year as invoices roll over - all while the cash never leaves the company's control until the moment of payment. Compare that to the same $500K sitting at 0.5% in an operating account, or paying down a credit line at 7.5%: the discounting program wins on yield, as long as the company can tolerate the cash being briefly illiquid each cycle.
Implementing a dynamic discounting solution takes four things in order: a cash forecast that tells you what's actually spare, an ERP integration so invoices flow without manual entry, a supplier onboarding plan, and a sign-off on the accounting and tax treatment before you launch.
On vendor choice, resist picking a platform just because you've heard the name. Match the platform to your funding model and scale, not the other way around.
| Criteria | Question To Ask | Why It Matters |
|---|---|---|
| Funding source | Is this my own cash, a bank partner, or a funding network? | Determines whether it's dynamic discounting or supply chain finance [10] |
| Minimum scale | How much invoice volume do I need before the platform pays for itself? | Small programs may not justify platform fees |
| ERP integration | Does it plug into my AP system or require manual uploads? | Drives onboarding time and supplier adoption [10] |
| Supplier reach | Does it work for long-tail small and mid-size suppliers, not just my top ten? | Those suppliers get the most value from early payment [13] |
| Fee structure | Flat platform fee, per-transaction fee, or a cut of the captured discount? | Directly affects your net yield on deployed cash |
If you'd rather not build the forecast and the vendor evaluation by hand, Dear CFO builds the cash forecast piece from your QuickBooks, so you know exactly how much is actually spare before you commit any of it to a discounting program.
A dynamic discounting solution is a real yield play, not a payment-terms nicety - the math regularly beats a credit line and often beats letting cash sit idle. But it only works if you've sized the program off cash you truly don't need, spread it across enough suppliers to avoid concentration risk, and built the ERP and forecasting plumbing before you turn it on. Run the numbers against your actual cost of capital, not a rule of thumb, and you'll know in one spreadsheet whether this belongs in your treasury toolkit.
It carries less risk than unsecured lending but it's not risk-free: you face counterparty risk on whoever owes the invoice, concentration risk if too much volume runs through one debtor (discounters often cap this around 30% of a ledger) [7], and liquidity risk if you need the cash back sooner than planned [6].
The main ones are traditional fixed early-payment discounts like 2/10 net 30, dynamic discounting with a sliding scale funded by the buyer's cash, supply chain finance (reverse factoring) funded by a bank at the buyer's credit rating [11], and invoice discounting or factoring where a third party funds against the supplier's receivable.
Dynamic discounting is a system where a buyer pays a supplier's invoice early in exchange for a discount that varies with how many days early the payment is made, funded directly with the buyer's own cash rather than external financing [4].
In supply chain finance, dynamic discounting works by linking approved invoices to a shared platform where suppliers choose from a menu of early-payment dates and matching discount rates, with payment released automatically once they select one [9][10]. It's recognized as one of the core techniques for accelerating payment across a supply chain [9].
Standard terms range from about 1% for payment 30 days early up to 3% or more for payment within 10 days, which annualizes to roughly 12% at the low end and over 56% at the high end depending on the terms [3]. Sliding-scale programs often quote a flat APR, like 10%, and prorate the discount by days paid early [2].

About the author
Partner, Phoenix Strategy Group
Ethan Lu is a Partner at Phoenix Strategy Group, where he works as a fractional CFO helping founder-led companies maximize their exit value. He currently oversees more than $200M in client enterprise value and has been part of multiple eight-figure exits. Before PSG he was an asset manager and investor for a San Diego family office, where he sat on the investment committee for more than $1B in assets. A data scientist by training, he holds a B.S. in Mathematics with a minor in Accounting from UC San Diego.
Talk to a PSG CFO about your numbers
Phoenix Strategy Group does CFO work for growth-stage companies.
Schedule a call