Published on
September 27, 2026

A financial ratio is just one number from your financial statements divided by another, built to answer a specific question: can you pay your bills, how much debt are you carrying, how profitably are you running the business. On their own the numbers on a balance sheet or income statement don't tell you much. Ratios turn them into signals you can track over time and compare against a benchmark.
Most guides to financial ratios are written for someone picking stocks, which is why they lean on giant public companies as examples. That's not you. You're running a $2M-$50M business, you probably don't have a public share price, and the ratio that actually affects your life is the one your bank is watching in your loan covenant, not the one an analyst is watching on a stock screener.
| Ratio | Formula | Category | Good range (varies by stage/industry) | What it signals to a lender or investor |
|---|---|---|---|---|
| Current Ratio | Current Assets ÷ Current Liabilities | Liquidity | 1.5-3.0 generally; ~0.9 can work for fast-turning retailers [1] | Can you cover short-term bills without new financing |
| Quick Ratio | (Current Assets − Inventory) ÷ Current Liabilities | Liquidity | Around 1.0 or higher | Can you cover bills without selling inventory |
| Debt-to-Equity (D/E) | Total Debt ÷ Total Equity | Leverage | Below 1.0 typical; above 2.0 common for capital-intensive businesses [2] | How much of the business rides on debt versus owner capital |
| Debt Service Coverage (DSCR) | Net Operating Income ÷ Total Debt Service | Leverage / Covenant | 1.25-1.5x is healthy [3]; SBA minimums run 1.1-1.15x [4] | Can cash flow cover the debt payments coming due |
| Fixed Charge Coverage (FCCR) | (EBITDA − Capex − Taxes) ÷ (Debt Service + Fixed Charges) | Leverage / Covenant | 1.0-1.25x minimum [5] | Cushion above the minimum obligations a lender requires |
| Return on Equity (ROE) | Net Income ÷ Shareholder Equity | Profitability | Varies widely by industry and leverage | How efficiently owner capital is generating profit |
| EPS | Net Income ÷ Shares Outstanding | Profitability / Valuation | Not a threshold; compare over time | Profit attributable to each share or unit |
| P/E | Share Price ÷ EPS | Valuation | Varies by growth rate and industry | What the market pays per dollar of earnings |
| EBITDA Margin | EBITDA ÷ Revenue | Profitability | Varies by industry; watch the trend | Core operating profitability before financing and accounting choices |
| AR Turnover | Net Credit Sales ÷ Average AR | Efficiency | Higher is better, relative to your payment terms | How fast you're converting sales into cash |
| Asset Turnover | Revenue ÷ Total Assets | Efficiency | Varies by industry (asset-heavy vs. asset-light) | How efficiently assets are generating revenue |
| Burn Multiple | Net Burn ÷ Net New ARR | Growth-stage | Below 2.0x is good [6]; typically 3.4x pre-$1M ARR down to 1.4x at $25-50M ARR [7] | Cash efficiency of growth spend |
| Rule of 40 | Revenue Growth % + Profit Margin % | Growth-stage | 40% or higher [8] | Whether growth and profitability are in balance |
| Net Revenue Retention (NRR) | (Starting ARR + Expansion − Churn − Contraction) ÷ Starting ARR | Growth-stage | ~100-110% for Series A companies [9] | Whether existing customers are expanding or shrinking |
| CAC Payback | CAC ÷ Monthly Gross Margin per Customer | Growth-stage | Median around 16 months, top quartile under 6 [10][11] | How long cash is tied up before a customer becomes profitable |
Notice the categories: liquidity, leverage, profitability, efficiency, and a fifth bucket most textbooks skip entirely: growth-stage metrics. If you've raised venture money or venture debt, that fifth bucket often matters more to your board than your current ratio does. We'll come back to all five.
EPS (earnings per share) is net income divided by shares outstanding; ROE (return on equity) is net income divided by shareholder equity; P/E (price-to-earnings) is share price divided by EPS. Together they answer how much profit you're generating and how the market is pricing that profit, which matters most once you're raising outside capital or preparing for a sale.
Picture Meridian Services, a $10M-revenue B2B services company with $800,000 in net income and $2,000,000 in shareholder equity. Its ROE is 800,000 ÷ 2,000,000 = 40%. That's a strong number, but it's partly a function of a thin equity base carrying real debt, which is exactly why ROE has to be read alongside leverage, not by itself.
If Meridian has 1,000,000 shares (or membership units, if it's an LLC), its EPS is 800,000 ÷ 1,000,000 = $0.80 per share. EPS on its own is mostly useful for tracking the same company over time, or for comparing to a per-share number in a term sheet. It's not comparable across companies unless share counts are similar, which is a common trap in casual comparisons.
P/E only exists where there's a market price, so it's less relevant to a private $10M company day-to-day. It matters most when you're benchmarking against public comps for a valuation, or reverse-engineering what multiple a strategic acquirer might pay. A SaaS company trading at 25x earnings and a manufacturer trading at 10x aren't mispriced against each other; they reflect different growth and risk profiles, which is the whole point of the ratio.
EBITDA stands for earnings before interest, taxes, depreciation, and amortization. It's net income with financing costs, tax strategy, and non-cash accounting choices added back, so you're left with a cleaner read on how the core business performs before the effects of capital structure and accounting policy.
The definition of EBITDA in formula form: Net Income + Interest + Taxes + Depreciation + Amortization. For Meridian Services, that's $800,000 net income + $250,000 interest + $250,000 taxes + $400,000 depreciation and amortization = $1,700,000 EBITDA, roughly a 17% margin on $10M of revenue.
EBITDA is the number buyers, lenders, and investors gravitate to because it lets them compare companies that finance themselves very differently, or that depreciate assets on different schedules. It's also the base most acquisition multiples are built on, which is why it matters even if you have no plans to sell this year. If a ratio somewhere ties back to an
acquisition multiple or valuation conversation, get comfortable with EBITDA now, not during diligence. For a deeper walk through how EBITDA and other valuation metrics translate into a purchase price, see this guide to valuation multiples using EBITDA and revenue metrics.
One caution: EBITDA is not cash flow. It ignores capex, working capital swings, and debt principal payments, all of which can eat a healthy EBITDA margin alive. A business can post a 20% EBITDA margin and still run out of cash if it's plowing that money into inventory or equipment. Treat EBITDA as a performance measure, not a cash forecast.
D/E, or debt-to-equity, is total debt divided by total equity, and it tells you how much of your business is funded by lenders versus owners. Most companies aim to stay below 1.0, though capital-intensive businesses like manufacturers and utilities routinely run above 2.0 without alarming anyone [2]. Whether your D/E is good depends entirely on your industry and how that debt is structured.
For a private growth-stage company, a D/E of 0.5 to 0.75 is generally comfortable: you're carrying meaningful debt but equity still covers it more than once over, and most lenders will treat that as low risk. A D/E of 1.5 means you have $1.50 of debt for every $1.00 of equity, which is workable for an asset-heavy business with steady cash flow but starts to worry lenders in a services or SaaS business with thin hard assets. Once D/E crosses 2.0, expect lenders to price you as higher risk and possibly ask for a personal guarantee, especially at smaller loan sizes [12].
Meridian Services, with $2,500,000 in debt against $2,000,000 in equity, has a D/E of 1.25. That's on the higher side for a services business, and worth watching, but it's not a crisis on its own. For a fuller walk through how to read and improve this number, see this breakdown of debt-to-equity ratio basics for growth companies.
Growth-stage companies rarely feel D/E directly; they feel it through covenants like DSCR (debt service coverage ratio) and FCCR (fixed charge coverage ratio). SBA lenders typically require a DSCR of at least 1.1 to 1.15x [4], while a DSCR of 1.25 or higher is considered genuinely healthy and 1.5x or above usually earns better rates [3]. FCCR minimums typically sit around 1.0 to 1.25x [5]. Some lenders also cap total debt at roughly $4 for every $1 of net worth for an established business [13].
The current ratio is current assets divided by current liabilities, and it answers whether you can pay what's due in the next 12 months out of what you can convert to cash in that same window. A ratio of 1.5 to 3.0 is generally considered healthy, though a retailer with fast inventory turns can run comfortably closer to 0.9 [1].
To calculate the current ratio for Meridian Services: $2,400,000 in current assets ÷ $1,200,000 in current liabilities = 2.0. That's solidly in the healthy range and gives Meridian real breathing room if a customer pays late or a big expense lands unexpectedly.
The quick ratio, sometimes called the acid-test ratio, strips inventory out of current assets because inventory isn't always quick to convert to cash. To calculate the quick ratio: (Current Assets − Inventory) ÷ Current Liabilities. For Meridian, with $300,000 of inventory: ($2,400,000 − $300,000) ÷ $1,200,000 = 1.75. Still healthy, and close enough to the current ratio that inventory isn't hiding a liquidity problem here.
Efficiency ratios measure how well you're converting assets, inventory, and receivables into revenue and cash, and they matter because two companies with identical profit margins can have very different cash needs depending on how efficiently they use working capital.
Accounts receivable turnover is net credit sales divided by average accounts receivable [14]. If Meridian books $9,500,000 in credit sales against an average AR balance of $1,400,000, turnover is roughly 6.8x, which works out to about 54 days of sales sitting in receivables. If your standard terms are net 30, that gap tells you collections are slipping, and it's usually the first sign of a customer quality problem or a billing process that needs tightening.
Asset turnover is revenue divided by total assets, and it shows how much revenue you're squeezing out of every dollar tied up in the business. Meridian's $10,000,000 in revenue against $6,000,000 in total assets gives an asset turnover of 1.67x. Asset-heavy businesses like manufacturers will run lower on this measure than asset-light services or software companies, so only compare this ratio within your own industry and against your own history.
Inventory turnover works the same way for product businesses: cost of goods sold divided by average inventory. A falling inventory turnover, alongside a rising current ratio, is a classic sign that
cash is quietly getting stuck in stock that isn't selling, which looks fine on a liquidity ratio and terrible on a cash flow statement.
Benchmark a ratio against three things at once: your own trend over the last 6-12 months, comparable companies in your industry, and the expectations tied to your capital structure. A ratio that's fine for a bootstrapped services firm can be a red flag for a venture-backed SaaS company burning investor cash, and vice versa.

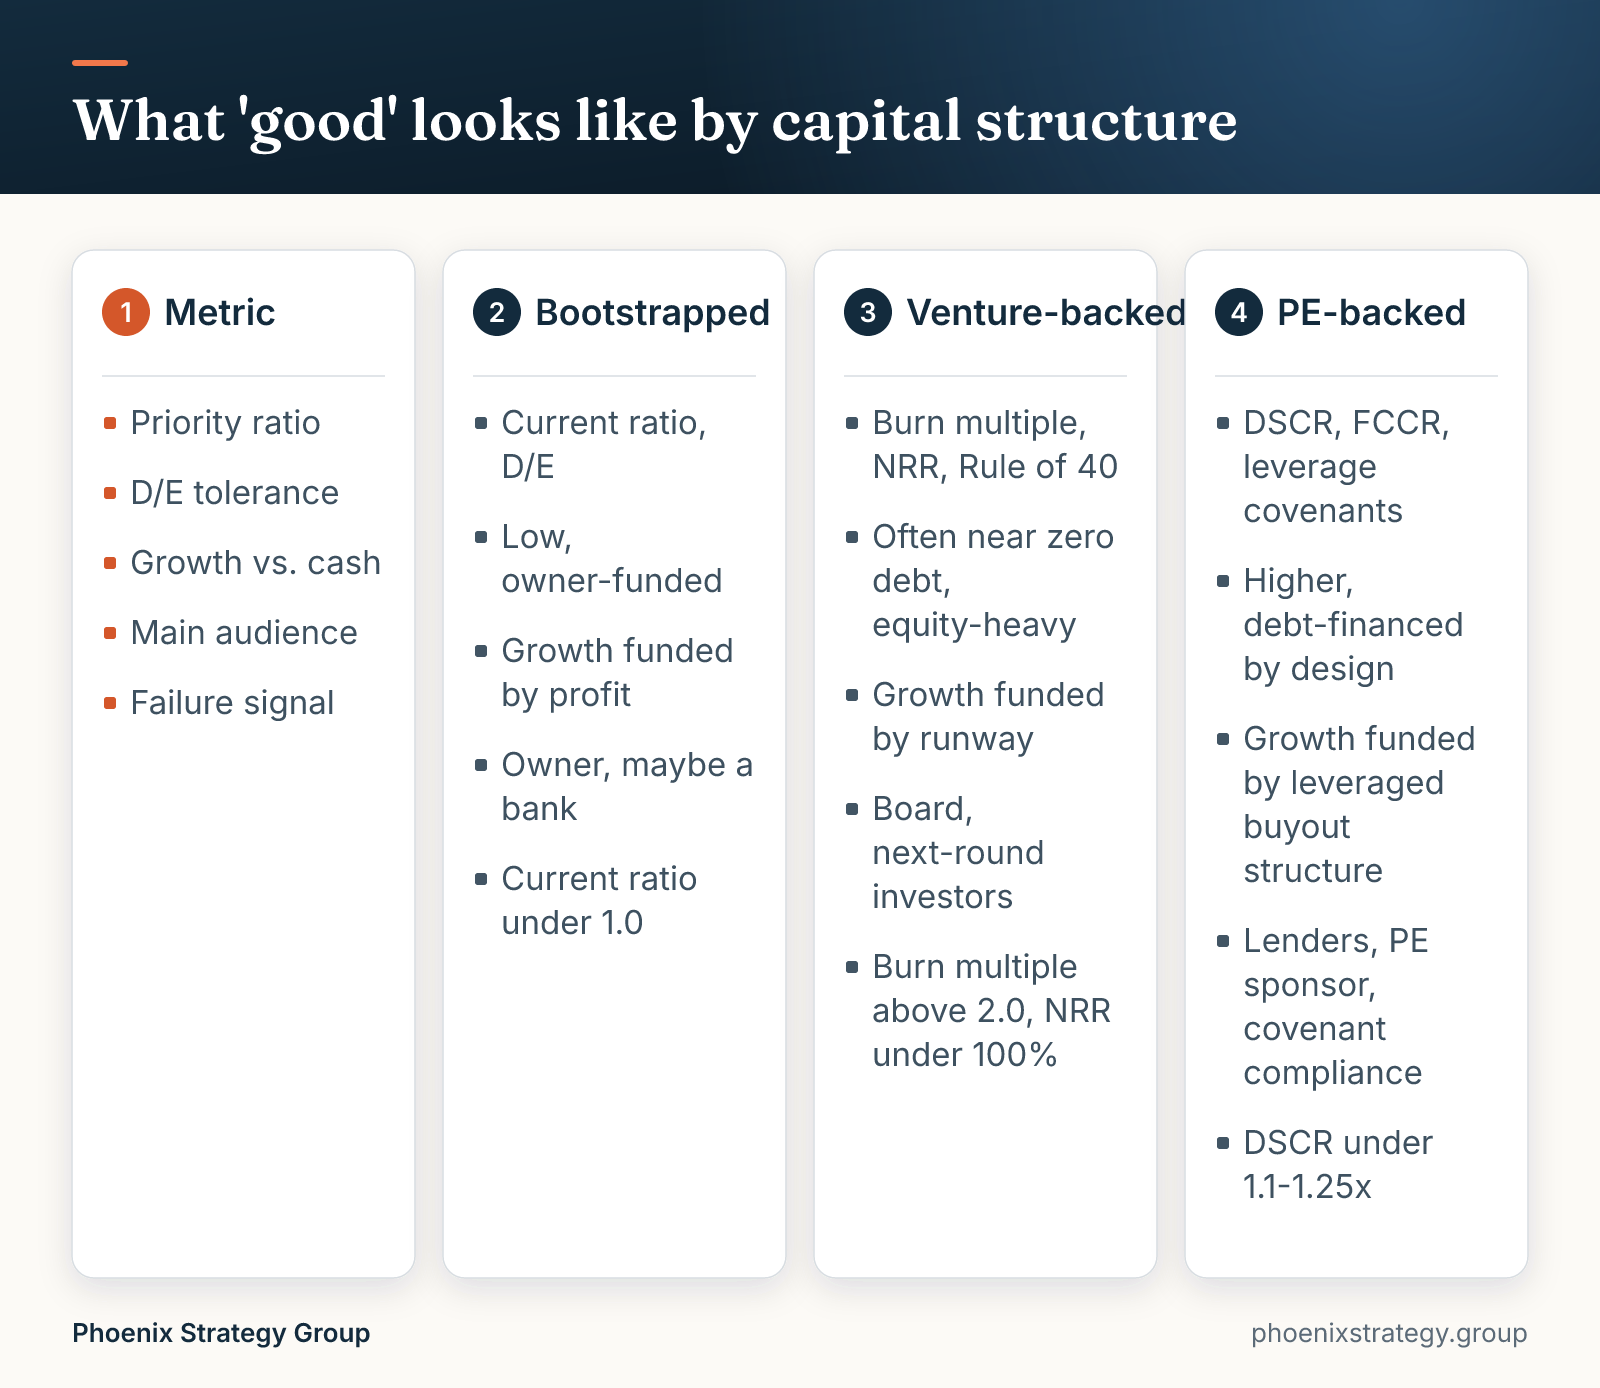
If you've raised venture money, four numbers matter as much as anything on the balance sheet. Rule of 40 says revenue growth rate plus profit margin should add to 40% or more for a healthy SaaS company [8], an idea popularized by investors like Brad Feld as a quick portfolio health check [15]. Burn multiple is net burn divided by net new ARR; anything under 2.0x is considered good for a venture-stage company, above that is suspect [6], and benchmarks shift with scale, averaging 3.4x for companies under $1M ARR versus 1.4x for companies between $25M and $50M ARR [7].
Net revenue retention (NRR) measures whether existing customers are expanding or shrinking; Series A investors generally want to see NRR approaching or exceeding 100%, with top performers around 110% [9]. CAC payback period, the months it takes to recoup customer acquisition cost, runs a median of about 16 months, with top-quartile companies under 6 [10], and many operators still plan around the older 15-18 month range [11]. Picture a SaaS company growing 30% a year with a -10% operating margin: its Rule of 40 score is 20, well under the 40% bar, which is exactly the kind of thing a board slide won't say out loud but a ratio will.
A monthly ratio review works best as eight to ten numbers, tracked against last month, last year, and your covenant thresholds, with a pre-agreed action tied to each one. The ratios matter less than having a rule for what you do when one moves the wrong way.
At $2M-$10M revenue, prioritize liquidity (current, quick) and basic leverage (D/E), because a cash crunch is the thing most likely to kill you. At $10M-$50M revenue, especially with a credit facility or institutional investors in the mix, covenant ratios like DSCR and FCCR move up the list, alongside growth-stage metrics if you're VC-backed. The mix shifts as your capital structure and audience shift, not on a fixed calendar.
Build this as a simple spreadsheet: one tab per month, one row per ratio, with your formula, current value, trailing trend, and a status flag. It doesn't need to be fancier than that to catch a problem early. If you'd rather not build this by hand and re-check it every month, Dear CFO builds it from your QuickBooks and keeps the trend line current automatically.
Financial ratios aren't a report card, they're an early warning system. The number itself matters less than whether it's moving the wrong way, and whether you've already decided what to do when it does. A current ratio of 2.0 or a D/E of 1.25 isn't good or bad in a vacuum; it's good or bad relative to your industry, your stage, and what your lender or investor is watching for. Pick eight to ten ratios, check them monthly against your own history, and set the trigger point before you need it, not after the cash is already tight.
Most CFOs would name current ratio, quick ratio, debt-to-equity, return on equity, and gross or EBITDA margin as the five to start with, covering liquidity, leverage, and profitability in one quick check. A growth-stage company would swap one in for burn multiple or NRR depending on its capital structure.
There's no single official list of 12, but a common set combines current ratio, quick ratio, D/E, DSCR, ROE, ROA, EPS, P/E, gross margin, EBITDA margin, AR turnover, and asset turnover, spanning liquidity, leverage, profitability, valuation, and efficiency.
Beyond the four core categories, analysts sometimes split ratios into liquidity, leverage, efficiency, profitability, valuation, coverage (covenant-specific ratios like DSCR and FCCR), and growth-stage or operational ratios like Rule of 40 and CAC payback, which is the seventh bucket most public-market guides skip.
The four main categories are liquidity ratios (can you pay short-term bills), leverage ratios (how much debt you carry relative to equity or cash flow), profitability ratios (how much you're earning relative to revenue or equity), and efficiency ratios (how well you're using assets and working capital).
For a private growth-stage company, 0.5 to 0.75 is comfortable and generally reassures a lender, since equity covers debt more than once over. Most companies aim to stay below 1.0 overall, though capital-intensive industries like manufacturing routinely run above 2.0 without it being a problem [2].
A D/E of 1.5 means you're carrying $1.50 of debt for every $1.00 of equity, which is workable for asset-heavy businesses with steady cash flow but starts to concern lenders in asset-light services or SaaS businesses. A high D/E generally signals higher risk to a lender, and once it crosses 2.0, expect closer scrutiny or a personal guarantee requirement, especially for smaller loans [12].
D/E stands for debt-to-equity, a leverage ratio calculated as total debt divided by total equity. In business it tells an owner or lender how much of the company is funded by borrowed money versus owner capital; in investing it tells a shareholder how much financial risk is layered on top of the operating business.

About the author
Partner, Phoenix Strategy Group
Ethan Lu is a Partner at Phoenix Strategy Group, where he works as a fractional CFO helping founder-led companies maximize their exit value. He currently oversees more than $200M in client enterprise value and has been part of multiple eight-figure exits. Before PSG he was an asset manager and investor for a San Diego family office, where he sat on the investment committee for more than $1B in assets. A data scientist by training, he holds a B.S. in Mathematics with a minor in Accounting from UC San Diego.
Talk to a PSG CFO about your numbers
Phoenix Strategy Group does CFO work for growth-stage companies.
Schedule a call