Published on
September 10, 2025

If you're reading this, you're probably past the point of asking what HFT is. You're trying to figure out how long your production system should actually hold a position, and what happens to your capital, your compliance budget and your risk limits once you pick that number. Most of what's written about high-frequency trading covers strategy and market mechanics. Almost none of it covers trade duration as an operational decision a finance leader has to sign off on. That's what this post is for.
Trade duration is the length of time a position stays open, from the moment your algorithm enters a trade to the moment it closes it out. In production HFT systems, holding periods run from a few microseconds for market-making quotes up to a few minutes for some statistical arbitrage books [1]. The number that matters for a CFO isn't how fast your code executes an order. It's how long you choose to be exposed to the market once that order fills.
Most of what gets written about HFT treats speed and duration as the same thing. They're not. Latency is how quickly your system reacts to new information, measured in microseconds. Duration is how long you keep a position on your book once you've opened it. A market maker might react to a quote update in microseconds but hold the resulting position for half a second while it works out of inventory. An arbitrage strategy might react just as fast but close the position in under a minute once the price gap it's exploiting closes [1]. Co-location and low-latency infrastructure shrink the time it takes to establish and liquidate a position [2], but they don't decide how long you sit on that position. That's a separate choice, and it's the one this post is about.
Treat trade duration as a dial you set on purpose, tied to your risk tolerance, your capital base and the strategy you're running, not as an accident of whatever your engineering team happened to build. Get that dial wrong and you'll either leave money on the table by holding too long and giving your edge back to slippage, or burn cash on infrastructure you don't need by chasing microseconds for a strategy that doesn't require them.
Your target trade duration should come from three inputs: your capital base, how much risk you can tolerate per position, and which strategy family you're running. Market making, arbitrage and momentum trading each have a natural duration range, and the right move is to pick the shortest duration your edge and infrastructure can actually support, not the shortest duration that's technically possible.
Market making generally holds inventory for the shortest windows, seconds at most, because the strategy's whole point is to avoid directional exposure while capturing the spread. It needs ultra-low latency and dynamic pricing to manage that inventory risk in real time. Arbitrage strategies close positions once the price gap they're exploiting disappears, which can take anywhere from milliseconds to under a minute [1]. Momentum and news-based strategies typically hold longer, seconds to a few minutes, and care less about shaving microseconds off execution and more about being early on direction.
Capital base drives this too. A small desk can't easily justify co-location fees running $12,000 a month or more plus installation [3], so it makes more sense to run a seconds-to-minutes strategy off a cheaper, consolidated data feed instead of a premium direct feed [4]. A larger book can amortize that fixed infrastructure cost across enough volume that sub-millisecond duration starts to pencil out. Neither answer is wrong; it depends entirely on the volume you can push through the system, which is exactly the calculation in section 4.
Shorter duration bands generally require more fixed infrastructure spend and higher turnover-driven fee drag, while longer bands need less infrastructure but tie up more capital per position because you're carrying directional risk for longer. The trade-off is roughly linear: the closer you get to sub-millisecond holding periods, the more your cost structure shifts from capital risk to fixed technology cost.
| Duration band | Typical strategy | Capital intensity | Infrastructure cost | Turnover / fee drag |
|---|---|---|---|---|
| Sub-millisecond | Market making, quote adjustment | High volume of small positions | Co-location plus direct feeds, $12,000+/month [3] | Very high, needs rebate capture to offset fees |
| Milliseconds | Latency arbitrage, stat arb | Medium-high | Co-location typically required [2] | High, strategy is fee-sensitive by design |
| Seconds | Stat arb, momentum ignition | Medium | Proximity hosting, professional data feeds ~$100-135/month per exchange [4] | Moderate, fewer round trips than sub-millisecond bands |
| Minutes | News-based, short swing | Low-medium, more directional exposure per trade | Consolidated feeds, retail-grade ~$10-15/month per exchange [4] | Lower, fewer trades but each carries more market risk |
Notice the pattern: as duration shrinks, fixed infrastructure cost goes up and per-trade capital risk goes down, because you're not exposed long enough for the market to move much against you. As duration grows, it flips. You spend less on technology but carry more directional risk per position and need more capital cushion to absorb a bad move before you exit.
Breakeven trade duration is the shortest holding period at which your expected edge per trade still covers your fixed infrastructure and data costs for that period. Divide your monthly fixed cost by your average edge per trade to get the number of trades you need, then check whether your strategy can realistically generate that volume at that duration. If it can't, go slower.
Picture a small proprietary desk running a market-making strategy on CME futures. It pays $12,000 a month for co-location plus a one-time $2,000 install [3], and runs professional-grade data feeds across three exchanges at roughly $130 each, another $390 a month [4]. Call it $12,390 a month in fixed infrastructure cost. Suppose the desk captures an average edge of $0.75 per round-trip trade after commissions. To break even on infrastructure alone, it needs about 16,520 trades a month, or roughly 790 trades a day across 21 trading days. If the strategy realistically clears 4,000 round-trip trades a day, monthly revenue lands around $63,000 against $12,390 in fixed cost, comfortably positive. If it can only manage 300 trades a day, the desk is paying for speed it can't use and would be better off on a slower duration with cheaper infrastructure.
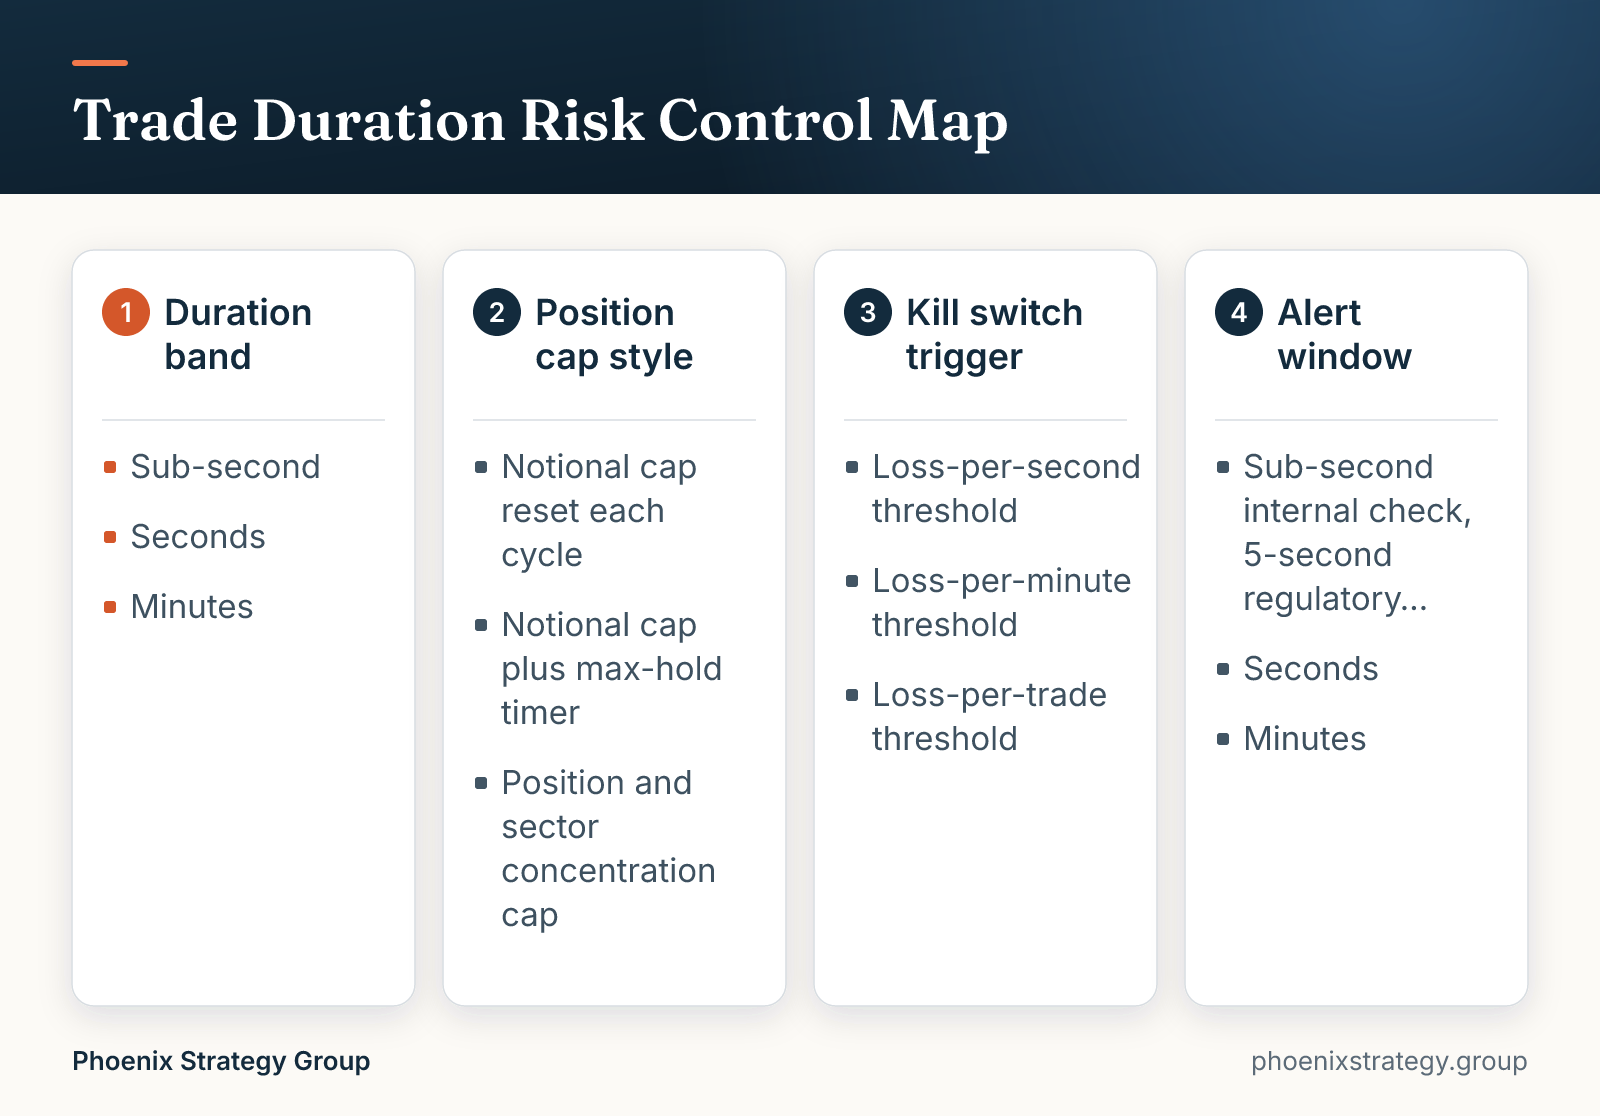
Every trade duration band needs its own risk limits, kill switches and monitoring thresholds; the same circuit breaker that protects a sub-second market-making book is either useless or dangerously slow for a five-minute momentum strategy. Set position caps, max holding time and alert windows by duration band instead of applying one blanket policy across the whole book.
Shorter trade duration usually means less capital tied up at any single moment because positions clear fast, which can lift capital efficiency and free up margin for other trades. It also raises turnover, and investors and regulators will expect you to explain that turnover explicitly, not bury it in a single P&L line.
Margin utilization is the clearest example. A book that flattens every position before the close needs far less overnight margin than one carrying positions for hours or days, which frees that capital for other uses between sessions. On paper, that looks like a better return on capital. The catch is that the fixed cost drag from section 4 doesn't disappear, so the net effect on your Sharpe ratio depends on whether your edge-per-trade comfortably exceeds your all-in cost per trade. If it barely does, shrinking duration further just adds noise without adding return.
When you report to investors or a board, be ready to show gross exposure, net exposure and turnover side by side, not just net P&L. A strategy that turns over capital fifty times a day looks very different on a risk basis than one that turns over twice, even if the monthly return numbers look similar. Investors who've seen HFT books before will ask about this before you finish the sentence.
Your holding period isn't just a trading decision, it's a compliance input. MiFID II and U.S. market access rules both set requirements that scale with how fast and how often you trade, and a CFO should budget for that overhead before scaling duration down, not after the fact.
Under MiFID II RTS 6, firms doing algorithmic trading are required to generate real-time alerts within five seconds of a defined triggering event, and to run pre-trade controls that include market and credit risk limits, maximum order volumes, execution throttles and price collars [5]. In the U.S., market access rules require brokers to prevent the entry of orders that exceed preset credit or capital thresholds in aggregate for each customer [6]. Neither rule set cares how clever your strategy is; both scale with trade count and speed, which means a book running sub-second duration needs meaningfully more surveillance infrastructure than one running on a five-minute clock.
Budget for this the same way you'd budget for co-location. Compliance headcount, monitoring tooling and audit trail storage all scale with trade volume, not assets under management. If you're planning to shorten duration to capture more edge, model the added compliance opex alongside the infrastructure cost from section 3, not as an afterthought once the desk is already live.
Shortening trade duration only pays off when the incremental edge you capture exceeds the incremental infrastructure and compliance cost. Use the breakeven volume from section 4 as your gate, and don't commit to co-location or direct feeds until you've proven the edge exists at a slower, cheaper duration first.
For a growth-stage fintech or trading-adjacent firm, the sensible build-vs-buy sequence is to prove the strategy on a retail or consolidated data feed, running $10 to $15 a month per exchange [4], before committing to a professional feed and eventually co-location at $12,000 or more a month [3]. If the strategy shows a real, repeatable edge at seconds-to-minutes duration on cheap infrastructure, that's your evidence to model the case for going faster. If it doesn't, no amount of speed will fix a strategy that doesn't have an edge to begin with.
As a decision rule, I'd want projected monthly trading revenue at the shorter duration to run three to five times the fixed infrastructure cost before committing capital to co-location, direct market access and the compliance build-out that comes with it. That margin covers build time, staffing, and the inevitable stretch where a new system isn't performing at its modeled edge yet. Anything tighter than that and you're betting the company's cash on an engineering timeline.
Very short trade duration creates a treasury problem most finance teams underestimate: margin calls can arrive and clear within minutes, so your cash and collateral buffers need to be sized for intraday swings, not just end-of-day balances.
Practically, that means real-time visibility into cash and margin, not a report that updates once a day. A book running sub-second or seconds-duration strategies can move its margin requirement meaningfully within an hour, and if your treasury process only checks balances at close, you'll find out about a shortfall after it's already a problem. Keep a buffer above the exchange's stated minimum margin, sized to your worst historical intraday swing, not the average one.
High trade count also makes daily reconciliation harder. With thousands of trades a day, matching your internal blotter to your clearing firm's records by hand isn't realistic, so this needs to be automated and reviewed as part of your daily close, not batched into a monthly review. And remember that capital sitting in a margin account isn't available for anything else. For a growth-stage firm weighing shorter trade duration against other uses of cash, that opportunity cost belongs in the decision, not just the infrastructure bill.
Latency, co-location and direct market access are engineering terms, but each one shows up on your financial statements somewhere, as opex, capex or a working capital drag. Here's the plain translation to have ready before you sign off on an infrastructure budget.
| Technical term | What it means | Where it hits your financials |
|---|---|---|
| Latency | Time between a market event and your system reacting to it, measured in microseconds [7] | Drives revenue upside or downside more than direct cost |
| Co-location | Renting server space inside the exchange's data center to cut network distance [S5, S7] | Fixed monthly opex, often $12,000 or more plus installation [3] |
| Direct market access (DMA) | A wired connection to the exchange that skips broker order routing [7] | Lower per-trade broker fees, but shifts risk-control and compliance burden onto you [6] |
| Market data feed | Direct exchange feed versus a consolidated retail feed [8] | Opex from roughly $10-15/month retail per exchange up to $100-135/month professional per exchange [4] |
| Trade duration | How long a position stays open once filled | Drives margin and collateral needs, and how much working capital sits tied up in open positions |
None of these line items are large on their own at a small scale. They compound fast once you're running a live book, which is exactly why they belong in the same model as your breakeven trade calculation, not in a separate engineering budget nobody in finance reviews.
Trade duration isn't a technical afterthought, it's a financial decision with a capital cost, an infrastructure cost and a compliance cost attached to every notch you shorten it. The firms that get this right pick a duration based on their capital base and edge, run the breakeven math before spending on speed, and calibrate risk controls to the duration band they're actually running instead of one blanket policy. Get the sequence backwards, funding infrastructure before proving the edge, and you'll spend real money chasing microseconds a strategy never needed. If you'd rather not build this model by hand, Phoenix Strategy Group works with growth-stage trading and fintech firms on exactly this kind of capital and infrastructure planning.
HFT systems execute in microseconds to milliseconds [9], with some strategies capable of thousands or even millions of orders per second [8]. Most HFT strategies hold positions for well under a minute, many closing out in a fraction of a second [1]. What people usually mean by "speed" is latency, or reaction time, which is a separate thing from how long a position stays open once it's filled.
The 3-5-7 rule caps risk on any single trade at 3% of account capital, limits total open exposure across all positions to 5%, and targets a minimum profit of 7% on winning trades [10]. It started as a retail risk-sizing heuristic, but the underlying logic, cap per-position risk, cap aggregate exposure, and require winners to outweigh losers by a set ratio, is exactly what a production desk should build into its own limits, calibrated to its capital base and duration band rather than a fixed percentage.
The 7% rule is a stop-loss guideline used mainly in position and swing trading: exit a losing position once it falls roughly 7-8% below your entry price [11]. It's designed for holding periods of days to weeks, so it doesn't translate directly to sub-second or sub-minute HFT duration bands, where loss limits need to be set in dollars per minute or dollars per trade instead of a percentage stop built for a multi-day hold.
No strategy's value comes from win rate alone, and a high win rate can still lose money. A trader who wins 90% of trades but risks far more on the losers than they gain on the winners can lose money overall despite being "right" nine times out of ten [12]. What actually matters is expected value: win rate times average win, minus loss rate times average loss, and short-duration strategies in particular need to check that math before assuming a high hit rate means a good strategy.

About the author
Partner, Phoenix Strategy Group
Ethan Lu is a Partner at Phoenix Strategy Group, where he works as a fractional CFO helping founder-led companies maximize their exit value. He currently oversees more than $200M in client enterprise value and has been part of multiple eight-figure exits. Before PSG he was an asset manager and investor for a San Diego family office, where he sat on the investment committee for more than $1B in assets. A data scientist by training, he holds a B.S. in Mathematics with a minor in Accounting from UC San Diego.
Talk to a PSG CFO about your numbers
Phoenix Strategy Group does CFO work for growth-stage companies.
Schedule a call