Published on
December 29, 2025

Someone just told you your business is worth
Someone just told you your business is worth
If you've spent any time reading valuation guides, you've probably noticed they were written for a $500,000 dropshipping store or a pre-revenue SaaS startup. Neither is much use if you're running a $12M services company, a $30M manufacturer, or a growth-stage business raising capital instead of selling outright. This post covers the methodology that actually applies between $2M and $50M in revenue: which method to use at which stage, what a good revenue multiple really means, and how to build the numbers a buyer or investor will trust.
What's different in 2026: EBITDA multiples in the $5M-$50M enterprise value band have held near 6.0x, roughly on par with the hot Q4 2021 market [1], while PE deal activity bounced back 37% year over year with North American buyout multiples near 11.9x EBITDA [2]. Meanwhile revenue multiples for SaaS have kept compressing, from about 17x in 2021 to roughly 3.8x by mid-2026 [3]. Translation: profitable, well-documented $5M-$50M companies are getting paid close to pre-2022 prices, but nobody is paying growth-only, unprofitable revenue multiples anymore.
With $1M in revenue, your business is probably worth somewhere between $200,000 and $2M, and that range is driven almost entirely by profit margin and business model, not the revenue figure itself. A $1M-revenue company earning $150,000 in owner profit, valued at a typical 2.5x-4x SDE multiple, lands around $375,000-$600,000. Revenue alone tells a buyer almost nothing without margin, growth, and retention layered on top.
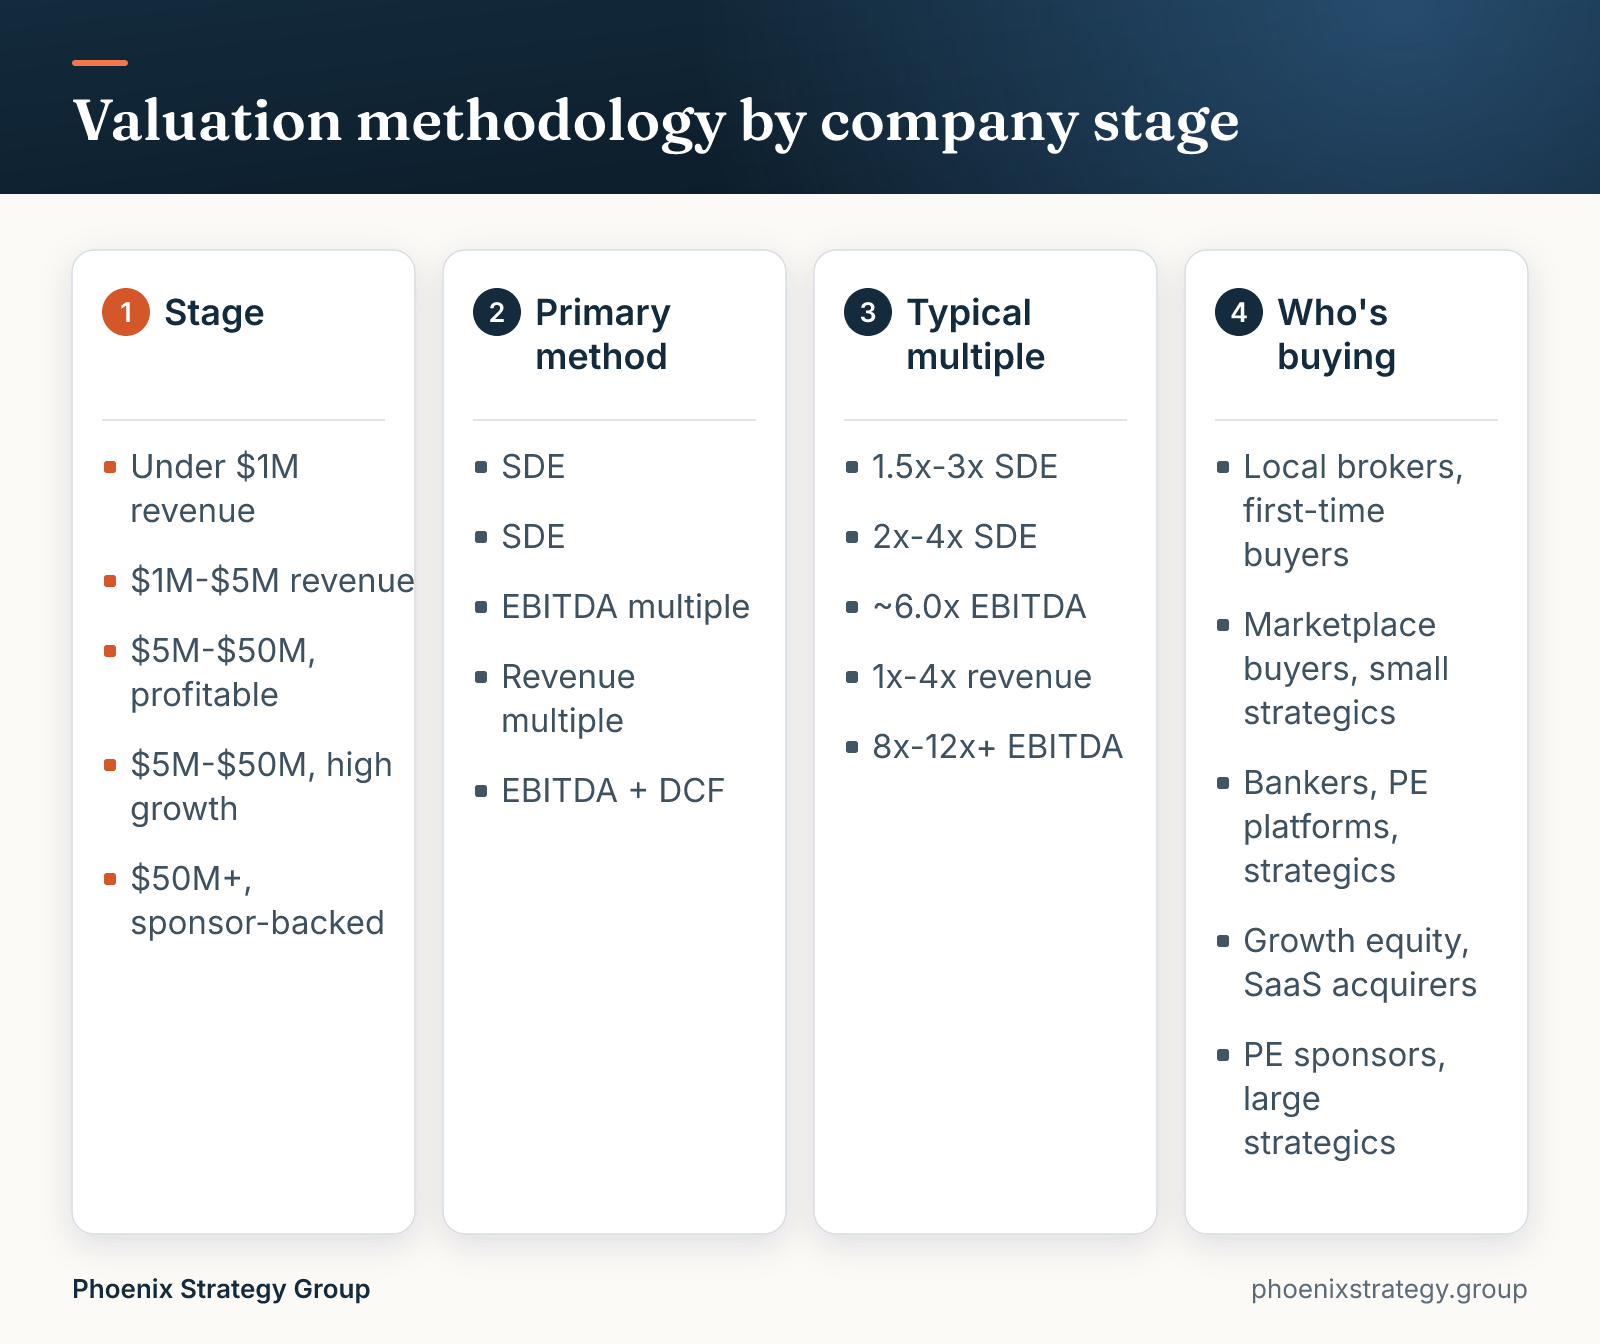
The method that applies to you changes as you scale, and using the wrong one is the single most common way founders misprice their own business. Below $1M in value, brokers price almost everything on Seller's Discretionary Earnings, the cash flow one working owner takes home, adjusted for owner pay and one-time costs. Ecommerce specifically sees a five-year average of 3.32x SDE [4], with industry SDE multiples ranging from 1.5x for thin-margin categories to 5x+ for recurring-revenue services [5]. Once EBITDA passes roughly $1M, buyers expect a management layer and start pricing on EBITDA instead, and that's also when the multiple itself jumps: SDE businesses trade at 2-4x, EBITDA businesses at 4-9x, for what can be very similar underlying cash flow [6].
| Revenue / EBITDA stage | Primary method | Typical multiple | Who's paying it |
|---|---|---|---|
| Under $1M revenue, owner-operated | SDE | 1.5x-3x SDE, industry dependent | Local brokers, first-time buyers [5] |
| $1M-$5M revenue, single owner | SDE | 2x-4x SDE, avg 3.32x in ecommerce | Business brokers, marketplace buyers [4] |
| $5M-$50M revenue, real management team | EBITDA multiple | ~6.0x EBITDA (Q4 2024 average) | Investment bankers, PE platforms [1] |
| $5M-$50M revenue, high growth or recurring | Revenue multiple | 1x-4x revenue, SaaS median 3.1x-3.8x | Growth equity, strategic acquirers [3] |
| $50M+ revenue, sponsor-backed | EBITDA multiple + DCF | 8x-12x+ EBITDA (NA avg 11.9x) | PE sponsors, strategic buyers [2] |
The three methods that show up in almost every real transaction are comparable multiples (SDE, EBITDA, or revenue, chosen by size and model), discounted cash flow, and precedent transactions. Most professional valuations lead with a recast multiple and use DCF as a sanity check rather than the headline number.
Pepperdine's 2025 Private Capital Markets survey found 76% of advisors lead with a recast EBITDA multiple, using DCF mainly to sanity-check or floor that answer [7]. That matters because it tells you where to put your energy: get your normalized earnings right first, then use a DCF to confirm you're not fooling yourself.
| Method | What it prices | Who uses it | Best for |
|---|---|---|---|
| SDE multiple | Owner's total cash benefit | Brokers, sub-$5M buyers | Owner-operated businesses under roughly $5M in EBITDA [6] |
| EBITDA multiple | Cash flow available to any owner | Investment bankers, PE, strategics | Companies with a management layer above $5M in revenue [8] [6] |
| Revenue multiple | Top line, adjusted for growth/margin/retention | Growth equity, SaaS and subscription buyers | High-growth or recurring-revenue models still ramping profit [3] |
| DCF | Present value of projected cash flows | Bankers and PE, as a sanity check | Confirming any multiple-based number isn't off [7] |
A good revenue multiple is a base multiple adjusted up or down for five things: growth rate, gross margin, net revenue retention, customer concentration, and the share of revenue that's recurring. Two companies with identical revenue can be worth twice as much or half as much once you stack those adjustments.
Start with an industry base, often 1x-4x for a growth-stage operating company. Add for above-average growth and gross margin. Add more for strong net retention, since it tells a buyer revenue this year predicts revenue next year. Subtract for customer concentration, since any customer over roughly 10-15% of revenue makes a deal harder to finance and many buyers walk away entirely [9]. Subtract for revenue that's one-time or project-based rather than recurring.
Stacked together, these five levers can move a company's valuation by roughly 80% at the same revenue and profitability [3]. That's the real answer to "what's a good multiple": it's not a single number you look up, it's a formula you build.
The Rule of 40 says a company's revenue growth rate and profit margin, added together, should be at or above 40% [10]. Score above 40 and you're rewarded with a multiple near the top of your band. Score well below it and buyers price you toward the bottom, or discount you outright.
The calculation is simple: growth % + margin %, using either EBITDA margin or free cash flow margin as the profit input [10]. A company growing 25% a year at a 20% EBITDA margin scores 45 and clears the bar. A company growing 10% at a 15% margin scores 25 and doesn't. This isn't a SaaS-only concept either; the same logic applies to any recurring or adjusted-revenue business, because buyers are really asking one question: are you buying growth, profit, or neither?
| Score | What it signals | Typical multiple impact |
|---|---|---|
| 60+ | Rare combination of growth and profit | Top of the band, premium pricing |
| 40-59 | Healthy, fundable business | Mid-to-upper band |
| 20-39 | One lever (growth or margin) is weak | Lower band, more diligence questions |
| Under 20 | Growth or profit story is broken | Steep discount, or priced mainly on DCF |
The compression is real and recent: the median public SaaS company traded at roughly 17x revenue in late 2021, fell to about 7.0x by the end of 2024, and sat near 3.8x by mid-2026 [3]. Most of that gap is companies that never cleared 40 in the first place getting repriced to reflect it.
Picture a founder running a $12M revenue B2B services company with a 17.5% EBITDA margin, or $2.1M in EBITDA. Run all three methods side by side and they should converge within a reasonable range, if your assumptions are sound.
On a revenue multiple, a services business without strong recurring revenue might land at 1x-2x revenue, putting the value at $12M-$24M, a wide range because revenue alone ignores margin. On an EBITDA multiple, using the Q4 2024 average of 6.0x for the $5M-$50M enterprise value band, that's $2.1M x 6.0 = $12.6M [1]. On a DCF, using a defensible discount rate in the 18-22% range typical for sub-$5M-EBITDA operating businesses [7], and projecting modest growth over five years, the answer should land somewhere near $12M-$14M as well, assuming terminal value assumptions aren't overly aggressive.
Where these converge, around $12M-$14M, is your defensible range. Where they diverge sharply, the revenue multiple is usually the outlier, because it doesn't account for margin at all. When a revenue multiple and an EBITDA-derived value disagree by a wide margin, trust the EBITDA number and the DCF, and treat the revenue multiple as a rough sanity check rather than your answer.
A normalized EBITDA schedule starts with reported net income and adds back non-operating and non-recurring items, one line at a time, until you're left with the cash flow a new owner would actually inherit. Buyers expect to see this schedule, not just the final number.
| Line item | Reported P&L | Adjustment | Why it's added back |
|---|---|---|---|
| Reported net income | $980,000 | — | Starting point |
| Owner salary above market rate | included as expense | +$220,000 | Owner paid above a replacement manager's market rate |
| Related-party rent | included as expense | +$90,000 | Owner's building leased to the company above market |
| One-time legal settlement | included as expense | +$140,000 | Non-recurring litigation cost |
| Family member payroll, non-market role | included as expense | +$65,000 | Compensation not tied to a market-rate job |
| One-time M&A advisory fees | included as expense | +$85,000 | Non-recurring deal costs from a prior process |
| Personal auto and travel | included as expense | +$40,000 | Discretionary, non-operating expense |
| Depreciation and amortization | included as expense | +$380,000 | Non-cash charge added back per EBITDA definition |
| Normalized EBITDA | — | — | $2.0M (roughly $2.1M with minor rounding) |
The same cash flow gets priced differently depending on who's buying, because strategics, PE platforms, search funds, and family offices are each underwriting a different question. Knowing which buyer you're actually talking to tells you how much room there is to negotiate the multiple.
| Buyer type | Typical multiple stance | How they finance it | What they underwrite |
|---|---|---|---|
| Strategic acquirer | Can exceed market multiple for synergies | Cash and/or stock | Customer/product overlap, integration risk |
| PE platform (control buyout) | Market multiple, EBITDA-focused | Leveraged: sponsor equity plus debt | Management depth, recurring revenue, add-on potential |
| Search fund / independent sponsor | Lower end of the band | SBA loan, seller note, small equity check | Owner transition risk, cash flow stability, low leverage tolerance |
| Family office | Patient capital, will pay for stability over growth | Equity-heavy, long hold period | Durability and lower risk, not maximum growth |
If you're a $12M-$50M revenue company preparing for a strategic sale, a recap, or growth capital, this is worth mapping out before you start a process, because it changes what you emphasize in the data room. A PE platform wants to see a management team that doesn't depend on you; a strategic wants to see customer overlap and integration ease.
The single biggest lever most founders ignore is time: the multiple you get depends heavily on what your financials and KPIs look like 12-24 months before a raise or sale, not the week you list. A handful of concrete moves reliably shift a company from the bottom of its band to the top.
There's no single "good multiple" that applies across every business. What matters is picking the method that fits your stage, building a defensible normalized EBITDA (or SDE) number, and understanding which five or six levers, growth, margin, retention, concentration, buyer type, actually move you within your band. A $12M revenue company can be worth $12M or $20M depending almost entirely on how well those levers are managed and documented.
Most of that work, clean financials, a KPI dashboard, a normalized EBITDA schedule, a defensible forecast, has to start well before a process, not during one. If you'd rather not build this by hand, Dear CFO builds it from your QuickBooks.
Somewhere between $200,000 and $2M, depending almost entirely on profit margin and model. A $1M-revenue company earning $150,000 in owner profit at a typical 2.5x-4x SDE multiple lands around $375,000-$600,000; revenue alone, without margin and growth context, isn't enough to price it.
Comparable multiples (SDE, EBITDA, or revenue depending on size and model), discounted cash flow, and precedent/market comparables. Most professional valuations lead with a recast multiple and use DCF mainly as a sanity check on that number [7].
A good revenue multiple is a base industry multiple adjusted for growth rate, gross margin, net retention, customer concentration, and how much revenue is recurring. Those adjustments, stacked together, can swing valuation by roughly 80% at the same revenue level [3].
The Rule of 40 says growth rate percent plus profit margin percent should add up to 40 or more [10]. Score above 40 and buyers price you near the top of your multiple band; score well below it and expect compression or a discount, a pattern behind the fall in SaaS multiples from around 17x in 2021 to about 3.8x in mid-2026 [3].
Ecommerce businesses average around 3.32x SDE over a five-year window [4], while the median disclosed SaaS M&A revenue multiple sits near 3.1x, with deals under $5M clearing around 3.3x [3]. Public SaaS multiples have compressed further, to roughly 3.8x revenue by mid-2026, down from about 7.0x at the end of 2024 [3].

About the author
Partner, Phoenix Strategy Group
Ethan Lu is a Partner at Phoenix Strategy Group, where he works as a fractional CFO helping founder-led companies maximize their exit value. He currently oversees more than $200M in client enterprise value and has been part of multiple eight-figure exits. Before PSG he was an asset manager and investor for a San Diego family office, where he sat on the investment committee for more than $1B in assets. A data scientist by training, he holds a B.S. in Mathematics with a minor in Accounting from UC San Diego.
Talk to a PSG CFO about your numbers
Phoenix Strategy Group does CFO work for growth-stage companies.
Schedule a call